
Wednesday, 28 October 2026 01:35 AM
Company Update
A Business Loan Sanction Is Not the Final Step - Understanding Pre-Disbursal Conditions
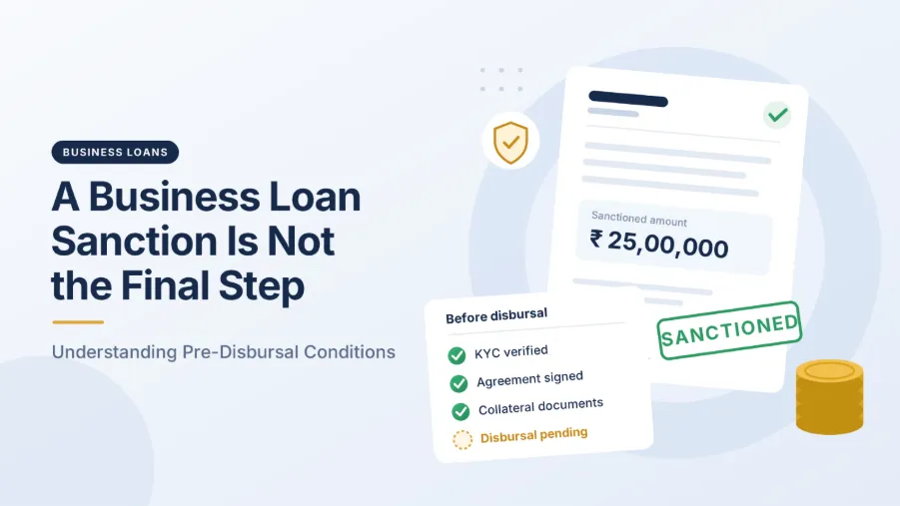
MUMBAI, IN / ACCESS Newswire / October 28, 2026 / A business loan sanction often feels like the hard part is over. The application has been reviewed, the lender has agreed in principle, and the terms are on paper. But sanction is not the same as fund release. Business loan disbursal usually happens only after the borrower accepts the terms, signs the agreement, and completes pending checks. This stage can feel procedural, but it matters a lot. So, in this article, we will cover the pre-disbursal conditions that help businesses avoid last-minute delays, plan vendor payments better, and stay ready for a smoother release of funds.
What Does a Business Loan Sanction Mean
A business loan sanction means the lender has approved the loan in principle, subject to the borrower accepting the terms and completing required formalities. It is an important milestone in the business loan sanction process, but it is not the same as receiving the funds.
At this stage, the lender may have reviewed:
- Eligibility
- Income
- Bank statements
- Credit profile
- Business continuity
- Repayment capacity
The sanction indicates the approved loan amount, tenure, interest rate, charges, repayment terms, and other conditions.
How is Sanction Different from Business Loan Disbursal
The difference is that sanction confirms approval, while business loan disbursal is the actual release of money to the borrower's account.
- Sanction confirms the loan amount, interest rate, tenure, charges, repayment terms, validity period, and conditions the borrower must meet before funds can be released.
- Disbursal happens after the required formalities are complete, including accepting the terms, completing documentation, and fulfilling any pre-disbursal conditions mentioned.
| Stage | Meaning | Borrower Action |
| Application | Loan request is submitted. | Provide details and documents. |
| Review | Lender reviews profile and eligibility. | Respond to queries or clarifications. |
| Sanction | Loan is approved in principle. | Review and accept the terms. |
| Pre-disbursal | Conditions are checked. | Complete documentation and formalities. |
| Disbursal | Funds are released. | Use funds as per the stated loan purpose. |
What Pre-Disbursal Conditions Do Lenders Check
Pre-disbursal conditions are the final checks that must be completed before the sanctioned loan is released. Business loan disbursal can be delayed if documents are pending, bank details do not match, signatures are incomplete, or the borrower has not accepted the final terms.
Common checks may include:
| Pre-Disbursal Check | Importance |
| Accepted sanction terms | Confirms that the borrower agrees to loan amount, rate, tenure, and charges. |
| Completed loan agreement | Creates the binding loan contract. |
| Updated Know Your Customer (KYC) details | Verifies identity, address, and borrower profile. |
| Bank account verification | Ensures funds are credited to the correct account. |
| Repayment mandate setup | Allows scheduled instalment collection. |
| Pending business loan required documents | Helps the lender complete verification before release. |
| Fee and charge confirmation | Ensures processing fee, stamp duty, or other applicable charges are clear. |
| End-use or purpose confirmation | Connects the loan to the stated business need. |
How Does the Business Loan Disbursal Process Work
The business loan disbursal process goes from business loan sanction letter acceptance to fund release in just a few short steps. They are as follows:
- The borrower receives and accepts the sanction terms, then completes the required documentation.
- The lender verifies the signed agreement, repayment mandate, account details, and any pending conditions.
- Upon meeting the pre-disbursal conditions the funds are released directly into the borrower's registered bank account.
- For disbursal that is linked to a specific loan type, end use, or lender policy, the timing and release method may differ.
How Can Borrowers Avoid Disbursal Delays
Borrowers can avoid delays by treating sanction as the start of the final review stage, not the end of the journey. A smooth business loan disbursal depends on clear documents, accepted terms, and quick responses to lender queries.
| Readiness Step | Points To Note |
| Read the sanction terms carefully | Check amount, tenure, rate, charges, and validity. |
| Compare EMI before accepting | Use a business loan EMI calculator to estimate monthly repayment. |
| Keep documents ready | Submit updated KYC, bank statements, tax records, and business proof where required. |
| Check repayment mandate | Ensure the linked account has correct details and sufficient balance. |
| Clear lender queries quickly | Delayed replies can slow down disbursal. |
| Review charges | Check processing fee, annualised cost, penal charges, and other costs in the KFS, where applicable. |
| Confirm the loan purpose | The stated end use should match the business requirement shared during the business loan approval process. |
Conclusion
A sanction is an important step, but it does not complete the loan journey. Business loan disbursal is the point where approval turns into actual access to funds. Until then, borrowers need to accept the loan terms, review the KFS where applicable, check charges, complete documents, verify account details, and set up repayment instructions. These actions may seem routine, but they can affect how quickly the loan amount is released. Borrowers who treat this stage seriously are better placed to receive funds smoothly and use them for the business purpose shared during application, without last-minute confusion, avoidable document gaps, or rushed decisions later.
Company Details
Company Name:
Kotak Bank
Contact Person: Kotak Bank
Email: [email protected]
Phone: 1800 4100
Address: Mumbai, Maharashtra, India
Website: https://www.kotak.bank.in/
SOURCE: Kotak Bank