
Tuesday, 29 September 2026 12:00 PM
Financing
They came of age as the pension was disappearing and worked through three crashes. Now they're telling pollsters exactly what they want.
SAN DIEGO, CA / ACCESS Newswire / September 29, 2026 / The first American generation to arrive at retirement largely without pensions has made up its mind about what it wants, and it wants a paycheck. Generation X, born roughly between 1965 and 1980, is turning in large numbers toward the one thing its parents had, and it never got: an income it can't outlive. The reasons aren't complicated. The pension disappeared just as Gen X started working. The crashes came in the years when a person is supposed to be compounding. And the generation is now standing at the edge of retirement with a record-sized 401(k), which one in four has borrowed against, and no obvious way to turn the balance into a monthly check. So, they have started buying the check. Americans bought a record $464 billion worth of annuities in 2025 and another $229 billion in the first half of this year, a first-half record, and the surveys explain who is doing the buying, and why.
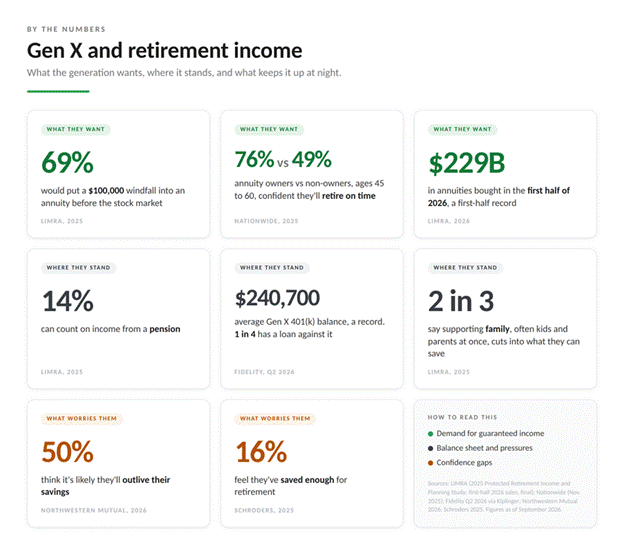
The clearest illustration is a question that pollsters in the retirement business like to ask, and it works a little like a parlor game. Suppose a hundred thousand dollars will land in your lap tomorrow. What would you do with it? In a 2025 study by LIMRA, the life-insurance industry's research arm, 69 percent of Gen Xers said they would use the money to buy an annuity, a contract with an insurance company that pays out a steady income, before they'd put a dollar of it in the stock market. Read that again. The generation that came of age with "Wall Street" in the theatres and the bull market of the nineties on the evening news, handed a windfall, would rather have a paycheck than a portfolio.
It helps to remember who these people are. This was the first cohort to spend its entire working life without the assumption of a pension. The 401(k) began as a footnote in the 1978 tax code, and the first plan built on it appeared in 1981, about the time the oldest Gen Xers were getting their driver's licenses. The traditional pension, the kind that sent a check every month until you died, was already on its way out of the private sector, and it left without much ceremony. Schroders, the British asset manager, puts the timing bluntly in its research on the generation: Gen X entered the workforce as employers were swapping pensions for 401(k)-style plans, and before automatic enrollment, the feature that quietly signs new hires up to save, became standard. Congress didn't bless automatic enrollment until 2006. By then the youngest Gen Xer was twenty-six and the oldest was forty-one.
So, they did it themselves, more or less, and they did it through a run of bad luck. The oldest of them started work around the crash of October 1987, when the Dow lost more than a fifth of its value in a single day. They were in their twenties and thirties when the dot-com bubble burst, and in their thirties and forties when Lehman Brothers failed, in 2008, and the market lost close to half its value over the months that followed. None of this is exotic; every generation gets its crashes. But Gen X got them at exactly the wrong ages, and it got them with no pension underneath.
The result is a generation that, on paper, has done reasonably well and, in its own telling, feels anything but secure. Fidelity, which administers retirement plans for tens of millions of workers, reported that the average Gen X 401(k) balance reached $240,700 in the second quarter of this year, a record. In the same report, about one in four Gen X savers were carrying a loan against that balance, a higher share than any other generation. Northwestern Mutual asked Americans this year whether they expected to outlive their savings; half of Gen X said yes, and one in five said money worries had already pushed back the date they plan to stop working. Schroders found that only 16 percent of Gen Xers feel they've saved enough. And Global Atlantic, an insurer, found that among the generation's first wave, the fifty-five- to sixty-year-olds now standing at the edge of retirement, 28 percent are extremely or very worried about having enough income to last their lifetimes, twice the rate among Boomers.
There is also the matter of everyone else. Two-thirds of Gen Xers told LIMRA that supporting relatives, often children and aging parents at the same time, is eating into what they can put away. Nearly half told Global Atlantic they expect to go back to work after they retire because they'll need the money. Among Boomers, one in five said the same.
• • •
What Gen X wants, then, is not mysterious. It wants the thing its parents had and it never got: a monthly amount it can count on, for as long as it lives, whatever the market is doing that year. In the retirement business, the product built for that purpose is the annuity, and the surveys suggest the generation has already made its peace with the idea. Nationwide, the insurer, surveyed nearly seven hundred people between forty-five and sixty in the summer of 2025, all of them still working and with at least a hundred and fifty thousand dollars in assets. Among those who already owned an annuity, 76 percent were confident they'd retire on schedule. Among those who didn't, 49 percent were. And the share of non-owners who said they were thinking about buying one had gone from 5 percent in 2023 to 31 percent two years later.
The industry has noticed. In February, LIMRA announced what it calls the Lifetime Income Initiative, a campaign aimed squarely at the sixty-five million members of Gen X. The insurer Transamerica has described 2026 as a potential tipping point, the year a record number of Americans in their early and mid-sixties look at their account balances and ask the one question a 401(k) statement can't answer: how do you turn this into a paycheck you can't outlive? More than 4.1 million Americans are turning sixty-five every year through 2027, a stretch the Alliance for Lifetime Income, an industry-backed nonprofit, has branded "Peak 65," and most of them have no pension. Gen X is next in line.
Where the money is going says as much as how much of it there is. The fastest-growing corner of the annuity market is a family of contracts that pay interest tied to a stock index but put a floor, or at least a buffer, under losses. LIMRA's description of the mood is as good as any: buyers "remain eager to participate in market growth but are wary of a downturn." That sentence could serve as the Gen X biography.
• • •
I've spent more than twenty years in this business, and I'll say plainly that an annuity is a trade, and it's worth knowing the terms. You hand an insurance company a sum of money, and it hands you a promise. The promise is only as good as the company making it; no government agency stands behind it the way the F.D.I.C. stands behind a bank deposit. Your money is usually committed for a period of years, and leaving early costs you a surrender charge. The growth is capped or shared with the insurer. Income riders, the add-ons that turn the contract into a lifetime paycheck, often carry an annual fee, and what your heirs receive depends on the payout option you chose at the start. For some households the trade is plainly worth it. For others it isn't, and the job of a good adviser is to tell you which you are.
In a piece I wrote earlier this year for Yahoo Finance, I looked at the countries whose retirement systems rank at the top of the world, the Netherlands and Iceland among them, and found that they all do the same two things. They invest their citizens' savings in the markets, for growth. Then they convert that growth into an income that lasts for life. Americans get the first half by default and have to build the second half on their own, and Gen X will be the first generation to do it with almost no pensions to lean on.
Which brings us back to the parlor game. It used to be that the question at the center of retirement was how big the account is. For Gen X, the question has shifted to whether the account will keep paying, every month, for as long as retirement lasts. Hand them a hundred thousand dollars and ask what they'd do with it. They've already answered.
Sources: LIMRA, 2025 Protected Retirement Income and Planning Study ("A Generation at Risk: Unpacking Gen X's Retirement Realities") and Lifetime Income Initiative announcement (Feb. 12, 2026); LIMRA U.S. Individual Annuity Sales Survey, full-year 2025 and second-quarter 2026 (final second-quarter figures as reported by PLANADVISER, Sept. 10, 2026, and InvestmentNews, Sept. 8, 2026); Global Atlantic 2026 Retirement Outlook Survey (April 1, 2026); Schroders 2025 US Retirement Survey, "Generation X and Retirement"; Northwestern Mutual 2026 Planning & Progress Study (April 1, 2026); Fidelity Investments Q2 2026 Retirement Analysis, generational breakdown as reported by Kiplinger; Nationwide Future Annuity Buyers Study (Nov. 19, 2025); Alliance for Lifetime Income, Peak 65 (2024); Transamerica commentary as reported by Annuity.org (Dec. 2025); Jan Gleisner, "The World's Best Retirement Systems Share One Habit. Americans Have to Build It Alone." (Yahoo Finance, June 23, 2026). Figures are the most recent available as of September 11, 2026.
ABOUT THE AUTHOR AND DISCLOSURES
Jan Gleisner is President of Hafnia Financial, Inc., a California-based registered investment adviser (CRD #315096), and holds insurance licenses (CA Insurance Lic. #0D77385). He holds the Series 65 and is President of Hafnia Insurance Services, Inc. (CA Insurance Lic. #6020269), an independent insurance agency in San Diego. His firm helps people near retirement build income strategies designed to last a lifetime. He can be reached at (858) 345-9001.
Mr. Gleisner and Hafnia Financial, Inc. receive advisory fees, and Mr. Gleisner also earns commissions from the sale of insurance products, including annuities. This creates a conflict of interest, because the strategies discussed here may be implemented through products that generate those commissions. Any reference to dependable or guaranteed lifetime income describes insurance products whose guarantees are subject to the claims-paying ability and financial strength of the issuing insurer. Such products are not insured or guaranteed by any bank or government agency and may involve fees, surrender charges, holding periods, and reduced access to principal. Insurance products and their availability vary by state. The author is insurance-licensed in California and multiple other states. Please consult a qualified tax professional or attorney regarding your individual tax and legal circumstances before making any decisions based on this article.
This article is for educational and informational purposes only. It is not personalized investment, insurance, tax, or legal advice, and it is not an offer or solicitation to buy any security or insurance product. Advisory clients of Hafnia Financial, Inc. are under no obligation to purchase insurance products through Mr. Gleisner or any affiliated entity. If you contact us, a licensed insurance agent may contact you. Survey and sales figures are from the third-party sources named in the article and were current as of September 2026. Full disclosures are available on request at [email protected].
SOURCE: Hafnia Financial